What is driving the global bond sell-off—and how does it reach the wider economy?
Global borrowing costs surged to multi-decade highs on October 1 before bond buyers stepped in and US yields retreated.
The US 10-year Treasury yield reached 5.34%, its highest since 2002, after recording its biggest quarterly increase this century, while selling pressure spread through France, Britain and Japan.[1][4] The yield later retreated toward 5.25% as bargain buyers entered the market and Federal Reserve of…
Open original (6 sources):
- [1] Yields fall after US 10-year hits highest since 2002; stocks, euro also decline - CNA — channelnewsasia.com
- [4] Global bond sell-off lifts US 10-year yield to highest level since 2002 - CNBC TV18 — cnbctv18.com
- [3] Treasuries Hold Gains After Rally, Stocks Decline: Markets Wrap - SWI swissinfo.ch — swissinfo.ch
- [5] Swings in the bond market shake stock markets worldwide, as AI optimism supports Wall Street - WXXV News 25 — wxxv25.com
- [6] US stocks rebound to close higher as surging Treasury yields recede - The Business Times — businesstimes.com.sg
- [2] US job growth expected to slow in September; unemployment rate likely steady | Business | lufkindailynews.com — lufkindailynews.com
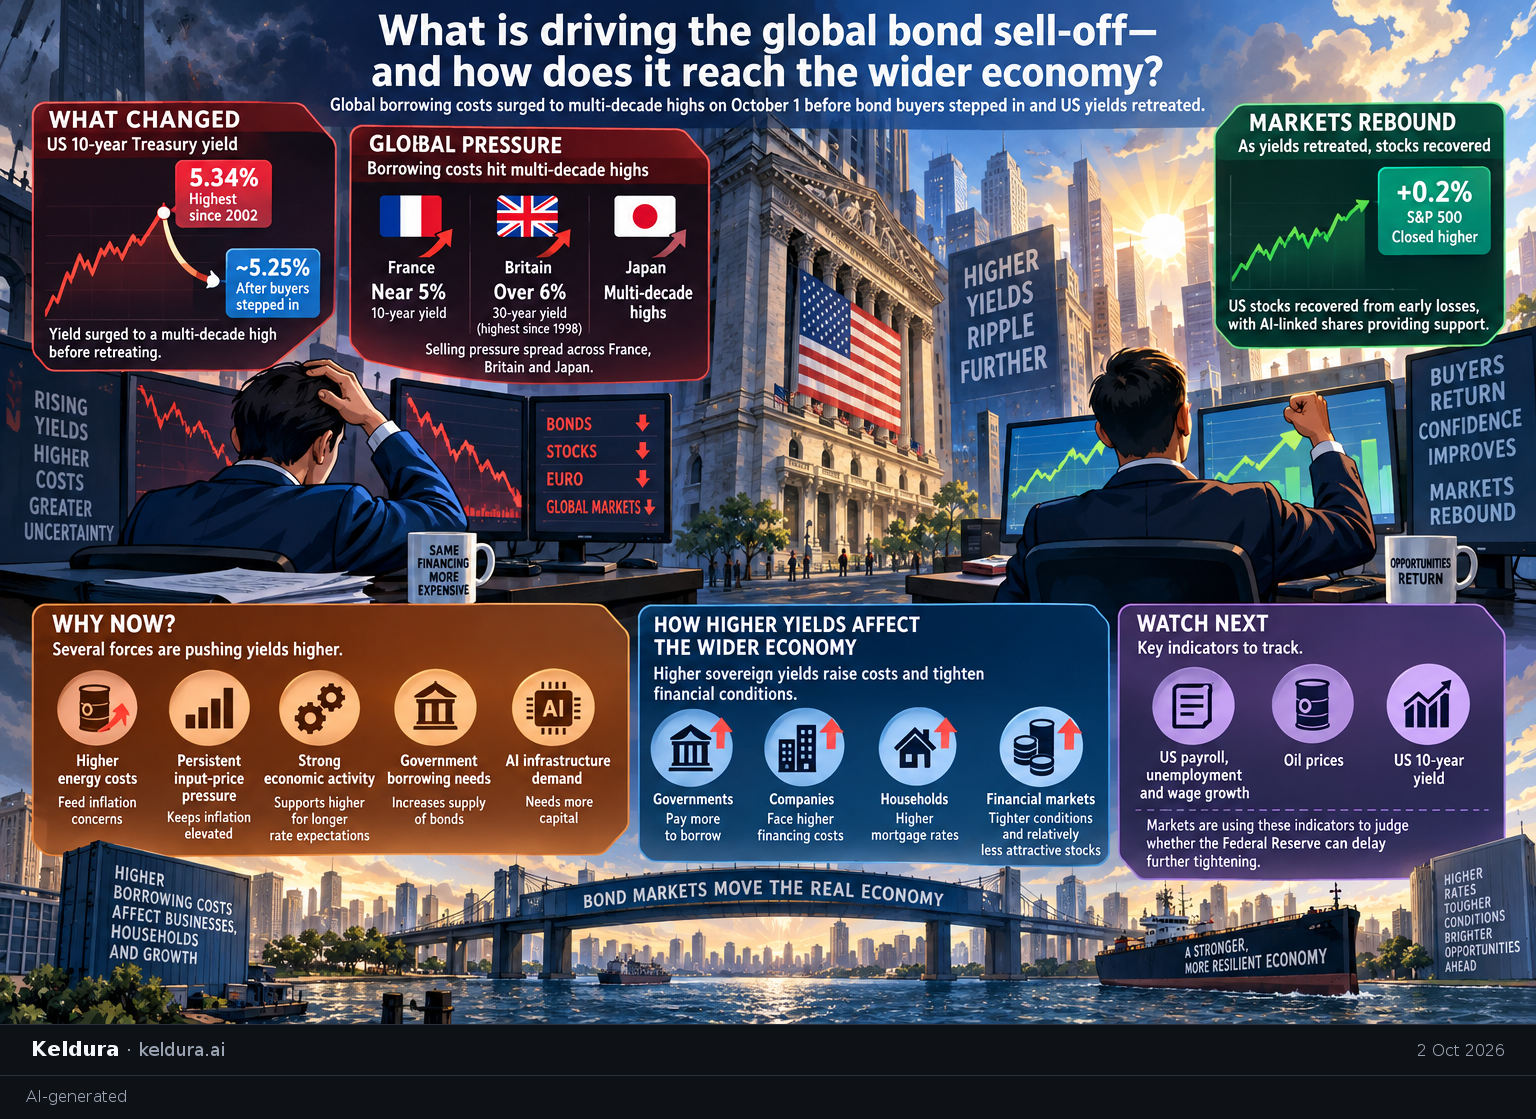
The US 10-year Treasury yield reached 5.34%, its highest since 2002, after recording its biggest quarterly increase this century, while selling pressure spread through France, Britain and Japan.[1][4] The yield later retreated toward 5.25% as bargain buyers entered the market and Federal Reserve officials signaled patience over additional rate increases; US stocks consequently recovered from early losses to close slightly higher.[3][5][6]
Why it matters: Higher sovereign yields raise financing costs for governments, companies and mortgage borrowers, tighten financial conditions and reduce the relative appeal of stocks; advanced economies already paid more than $3.3 trillion in interest on internationally traded government bonds over the past year.[4][5]
Key insights: The sell-off has several reinforcing drivers: elevated oil prices are feeding inflation concerns, AI and data-center construction are increasing demand for capital, and resilient economic activity is supporting expectations that interest rates will remain higher for longer.[1][4] | Europe is a particular pressure point: French 10-year borrowing costs approached 5%, the spread over German debt was near its widest since the euro-zone debt crisis, and Britain’s 30-year yield exceeded 6% for the first time since 1998.[4] | The reversal showed how sensitive equities are to bond yields: the S&P 500 recovered from a two-week low and closed 0.2% higher after the US 10-year yield pulled back, while AI-linked shares provided additional support.[5][6] | Near-term Federal Reserve expectations have softened despite the long-term yield surge: markets assigned a roughly 28% probability to an October rate increase, down from about 69% a week earlier.[2][6]
Cheatsheet facts: What changed: The US 10-year yield touched 5.34%, its highest since 2002, before retreating toward 5.25%; comparable selling pushed borrowing costs in France, Britain and Japan to multi-decade highs.[1][3][4] | Why now: Higher energy costs, persistent input-price pressure, strong economic activity, government borrowing needs and capital demand from AI infrastructure are collectively increasing inflation and interest-rate expectations.[1][4][5][6] | Watch next: Track the published US payroll, unemployment and wage-growth figures, alongside oil prices and the US 10-year yield; markets are using those observable indicators to judge whether the Federal Reserve can delay further tightening.[2][3]
X copy pack
Edition complete
You've reached the end of this edition.